Commercial auto insurers lost almost $5 billion on underwriting in 2024, making it the 14th consecutive year the line has run at a loss, according to FreightWaves. Insurers are passing the cost on to every contractor with vehicles on the road, whether you’ve filed a claim or not.
Before you panic, this doesn’t mean pricing is completely out of your hands. Underwriters price a fleet based on the risk they can see and document. Most contractors already run some type of safety program, but it doesn’t always show up in their premium, which can drive up insurance costs.
Here are five things you can do before your next renewal to move the needle to help lower your rate.
USE TELEMATICS TO EARN USAGE-BASED DISCOUNTS
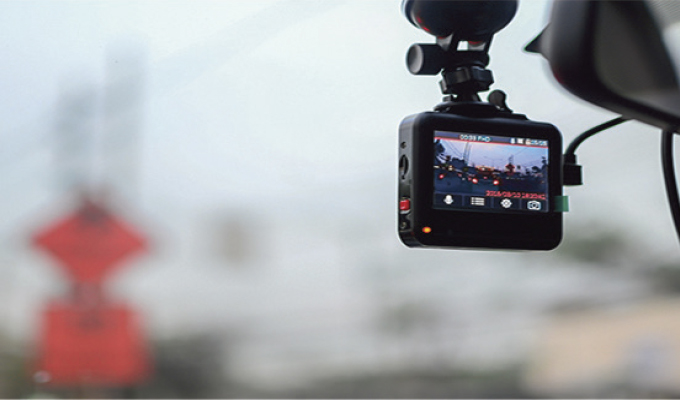
Telematics systems track hard braking, speeding, idle time, and mileage. Several carriers now price that data directly into renewals rather than treating it as an add-on. Telematics has also been proven to keep people safer. Distracted driving fell 8.6 percent nationally in 2024, preventing an estimated 105,000 crashes and 480 deaths, according to the Colorado Department of Transportation (CDOT). The agency partially attributes the drop in distracted driving to telematics systems and new in-vehicle technology. A basic GPS and dashcam bundle is often enough to qualify for an insurance discount, so you don’t need an enterprise-scale system to start.
The goal is not to introduce surveillance footage overnight and feel like employees are being watched. It’s to protect every driver and passenger who share the road with your fleet. Explain the purpose before installing the equipment. Tell drivers the primary goal is preventing crashes and coaching safer habits.
Installing telematics could help you avoid potential wrongful litigation because of an accident. Video can show traffic conditions, vehicle positioning, signals, and the moments immediately before impact. The information does not guarantee that your company will avoid liability, but when footage and data are preserved properly, it can help establish what happened and support a more defensible claim investigation.
AI TOOLS CAN PREDICT ACCIDENTS BEFORE THEY HAPPEN
As artificial intelligence improves, it’s getting better at identifying patterns and predicting when an accident could happen. For example, the Leif program continuously analyzes live workplace video and alerts employers to unsafe conditions before they happen. The program uses AI to detect a potential risk instead of relying on the historical loss data older predictive models use. When the system detects negative safety behavior, you’ll get a link to view context surrounding the event. Leif programs have driven a 35 percent reduction in workers’ compensation claims and helped many clients cut their total cost of risk by 20 to 30 percent, which can save you money.
MONITOR DRIVER MOTOR VEHICLE RECORDS CONTINUOUSLY
Insurance rates depend heavily on your driving record. Accidents, major violations, license suspensions, and other serious offenses can indicate an increased risk of a future loss.
An annual motor vehicle record (MVR) review is a minimum compliance requirement for many interstate commercial motor carriers. The Federal Motor Carrier Safety Administration says carriers must obtain an updated MVR at least once every 12 months and review it to confirm that the driver continues to meet safe-driving requirements and has no disqualifying offenses.
Continuous MVR monitoring can identify new violations sooner, allowing the employer to respond before the next annual review or renewal. Receiving an alert doesn’t automatically mean the employee must be terminated. The appropriate response depends on the offense, the driver’s history, the type of vehicle involved, applicable law, and the company’s written safety policy.
When should a driver be removed? A driver should generally be removed from driving responsibilities immediately when: their license, commercial learner’s permit, or CDL is suspended, revoked, or otherwise invalid; they receive a legally disqualifying offense; they test positive for alcohol or drugs under an applicable employer or regulatory program; or the company learns the driver cannot legally or safely perform the assigned driving duties.
The key is to define these standards before an incident happens and apply them consistently. A written response plan might look like this: a first violation to result in counseling and documented retraining, a second violation to trigger temporary removal, and a third violation to result in termination of driving duties.
SAFETY BONUSES AND INCENTIVE PROGRAMS
Incentives work when they reward the right behavior. You can build them around leading indicators, a completed inspection streak, or a clean scorecard average. A quarterly bonus tied to fleet-wide scorecard performance keeps the incentive pointed at prevention instead of concealment. Plus, it gives you a second data set to hand your underwriter alongside the scorecards themselves.
DOCUMENT THE PROGRAM FOR YOUR UNDERWRITER
If your insurance premiums are going up, it might be because your underwriters don’t know what safety tools or programs you have in place across your organization. Before your next renewal, compile a one-page summary that includes:
- Your written safety policy;
- Scorecard data that shows trends over time;
- Dashcam program details, including who reviews footage and how often;
- Your inspection compliance rate; and,
- A description of your incentive structure and what it rewards.
Hand that summary to your agent to submit alongside your renewal application, rather than mentioning the program in passing during the renewal call.
IMPLEMENT THESE SAFETY STEPS TO SAVE ON INSURANCE
Fleet insurance costs are influenced by more than your loss history. Carriers are looking closely at the systems you have in place to identify risky driving and unsafe behavior. The contractors in the best position at renewal are the ones who can prove they take fleet safety seriously every day.
While no safety program can guarantee lower premiums in a difficult commercial auto market, a strong, well-documented program can help you earn the best rate available for your operation and limit avoidable increases over time. It’s good practice to start pulling your documentation together 60 to 90 days before your renewal date instead of the week of the call. This will give your agent time to shop your program to carriers that reward prevention data and gives you time to close any gaps.
about the author
Robert Worden, CSD, construction risk advisor at Powers Insurance and Risk Management, which helps construction contractors package their existing safety efforts into a submission-ready summary to receive the highest chance of available discounts. Their team can help you gather the documentation underwriters want to see and identify gaps in your fleet safety program. Powers Insurance’s consultative approach makes it easy for contractors to improve their risk management, which can reduce claims and control insurance costs over time. To learn more, visit www.powersinsurance.com/business/construction-risk-management.